BEHAVIOURAL ANALYSIS FOR LENDERS · BUILT FOR AMLR
Customer due diligence that sees the person behind the deal.
Key Insights makes lenders’ onboarding AMLR-ready and analyses how customers describe their own business and loan, compared with registry data. The result is better input for onboarding, credit decisions and early collections.
Decision support for credit and compliance teams. The final decision is always yours.
Example with a fictitious company.
USE CASES
One engine, three use cases
Start where the need is greatest. The same analysis follows the customer from the first application to repayment.
Onboarding that reads between the lines
Registry data is retrieved automatically and the customer confirms it instead of filling it in. Open questions are checked against the registries in real time, discrepancies are flagged and everything is documented for AMLR.
- Discrepancy report and risk class input
- Beneficial owners, PEP and sanctions via partner
- Ongoing monitoring and reclassification
- Works on top of your existing onboarding
Built for AMLR, (EU) 2024/1624
Decision support for a second look
Credit officers get structured insight into ownership, realism in forecasts and the ability to execute the plan, alongside the financial ratios. Borderline cases can get a second look instead of an automatic no.
- Behavioural indicators that complement the ratios
- ML models trained on your own outcomes
- Evidence and quotes behind every insight
- For lending to companies
Decision support, never automated decisions
Prioritise where the conversation makes a difference
In early collections it is hard to see which customers can and want to pay. Analysing the customer dialogue gives a prioritisation based on ability to pay, willingness to pay and signals in the dialogue.
- Prioritisation of cases 1–90 days past due
- Input for the right approach in the dialogue
- Traceable reasoning for every case
- The same engine as in onboarding
Decision support for your collections team
The same engine works wherever people describe their business in their own words.
HOW IT WORKS
An engine that checks the customer’s words against the registries
The engine takes in registry data and the customer’s own answers, reconciles them and adds behavioural indicators. The result is a ready-to-review file for your credit officers or compliance team.
Data and the customer’s answers
Reconciliation and behavioural analysis
A ready file for your team
BETWEEN THE LINES
The engine reads the whole dialogue together with the registries
Every answer is checked against the registries and against the customer’s other answers. Contradictions, people who do not appear in the registries and language that changes character are flagged with a reference to exactly what the customer said.
Based in part on research on unexpected follow-up questions: Hartwig, Granhag et al. (2005) and Vrij et al. (2009).
File for the credit officer
A short or nervous answer is not enough for a flag. The engine first asks a follow-up question and then weighs the whole dialogue against the registries.
GETTING STARTED
From the first meeting to live operation
You see what the engine finds in your own cases before anything in your process changes.
-
1
Mapping
We review your onboarding flow against AMLR and agree which steps the engine takes care of.
-
2
Shadow run
The engine runs on 25–50 of your existing cases, alongside your own process.
-
3
Integration
We connect the engine to your existing application, or you use our chatbot.
-
4
Live operation
Your credit officers and compliance team get ready files. You make the decisions.
BUILT FOR REGULATED LENDERS
Security and compliance from the start
A person always decides
Key Insights is decision support, not automated decision-making. Every flag shows its basis, with source, rule and quote, so that a person can weigh it.
AMLR-ready from day one
The onboarding process and data handling are built for AMLR, (EU) 2024/1624.
Traceable at every step
An audit trail with source, time and applied rule for every data point and decision.
Built to ISO 27001/27002
AES-256 encryption at rest, two-factor sign-in and role-based access.
GDPR by design
A data processing agreement with documented sub-processors. The platform has been reviewed by a lawyer.
Data stays in the EU
All data is stored and processed in Stockholm, Sweden.
Designed for the AI Act
Transparent logic, documented rules and human review of every file.
ABOUT US
The numbers show what a company has done. The person behind it decides what it will do.
Sources: AMLR, (EU) 2024/1624 · Brå (Swedish National Council for Crime Prevention) · Key Insights review of Swedish SME lenders’ 2024 annual reports.
Annual accounts show how last year went. A credit report shows whether someone has missed a payment. How a company handles the years ahead is still decided by the person running it.
The person behind the business makes the decisions, sets the plans and handles the setbacks. That is also where the purpose of the deal becomes clear: what the money will actually be used for, who is in control and where the business is heading. Understanding the purpose of the customer relationship is exactly what AMLR requires you to assess and document.
Yet most onboarding flows are built on rigid forms and checklists. Customers fill in details that already exist in the registries, credit officers search for discrepancies by hand and the process becomes long for everyone. Checks that tick off registries and lists rarely meet today’s requirements, while money laundering keeps finding new ways in, often through companies that look perfectly ordinary on paper.
The result is a balancing act. Lenders must follow the rules without making it hard to become a customer, stop money laundering without screening out good customers, and keep losses down without rejecting companies that lack a long track record.
The ones who most often get caught in the middle are skilled entrepreneurs.
A young company, an unusual business model or a temporary dip is enough for a case to stall in manual review or be rejected automatically. Often the customer gives up before anyone has understood who the entrepreneur is and what the company is meant to become.
That is why Key Insights exists. We make the person behind the deal visible, in a way that can be reviewed and documented. Customers describe their business in their own words, and the engine checks it against the registries and highlights what does not add up. The process stays simple for the customer and thorough for you, so you can say no to the wrong customers sooner and yes to the right ones more often.
WHO WE ARE
Credit expertise and behavioural science in one team
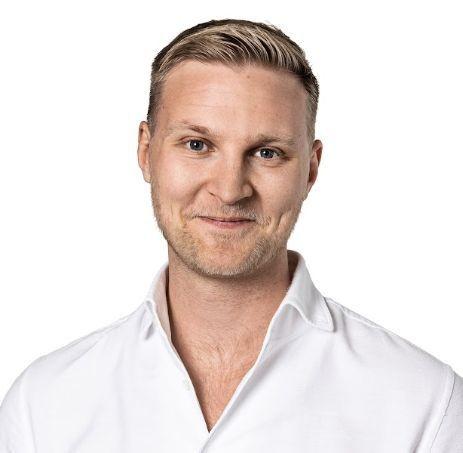
Martin Branzell
CEO AND FOUNDERFirst employee at Krea Technology, Sweden’s and Finland’s largest business-loan broker. Seven years in business development and bank partnerships across Sweden, Finland and the Baltics, with a seat on the management team.
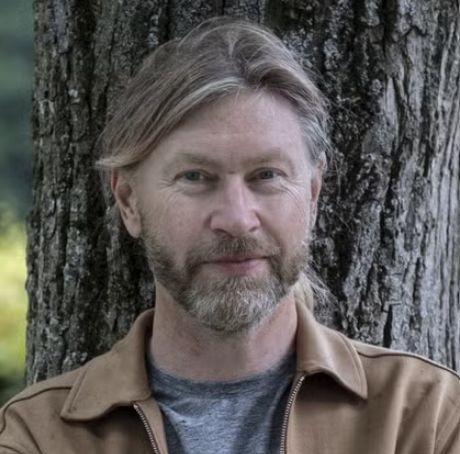
Sverker Sikström
CO-FOUNDER, AI AND TECHNOLOGYProfessor of cognitive psychology whose research field is AI-based language analysis. Leads the development of the engine and of TalkToAlba, where the same technology is already in live use.
CONTACT
See the engine read your own cases
Book a demo and we will walk through your onboarding flow and show what the engine finds in a selection of your cases.